Investment accounting transformation: key findings
Where product complexity, NAV resilience and platform fragmentation are reshaping investment accounting.
In Partnership with

Content Types
Topics
SHARE THIS INSIGHT
Sponsored by FIS®, these key findings show that T+1 dealing cycles are now a leading concern for NAV resilience, while firms are increasing focus on contingent delivery models, accelerated production and the cost of operational change.
Growth is shifting away from equities
Product mix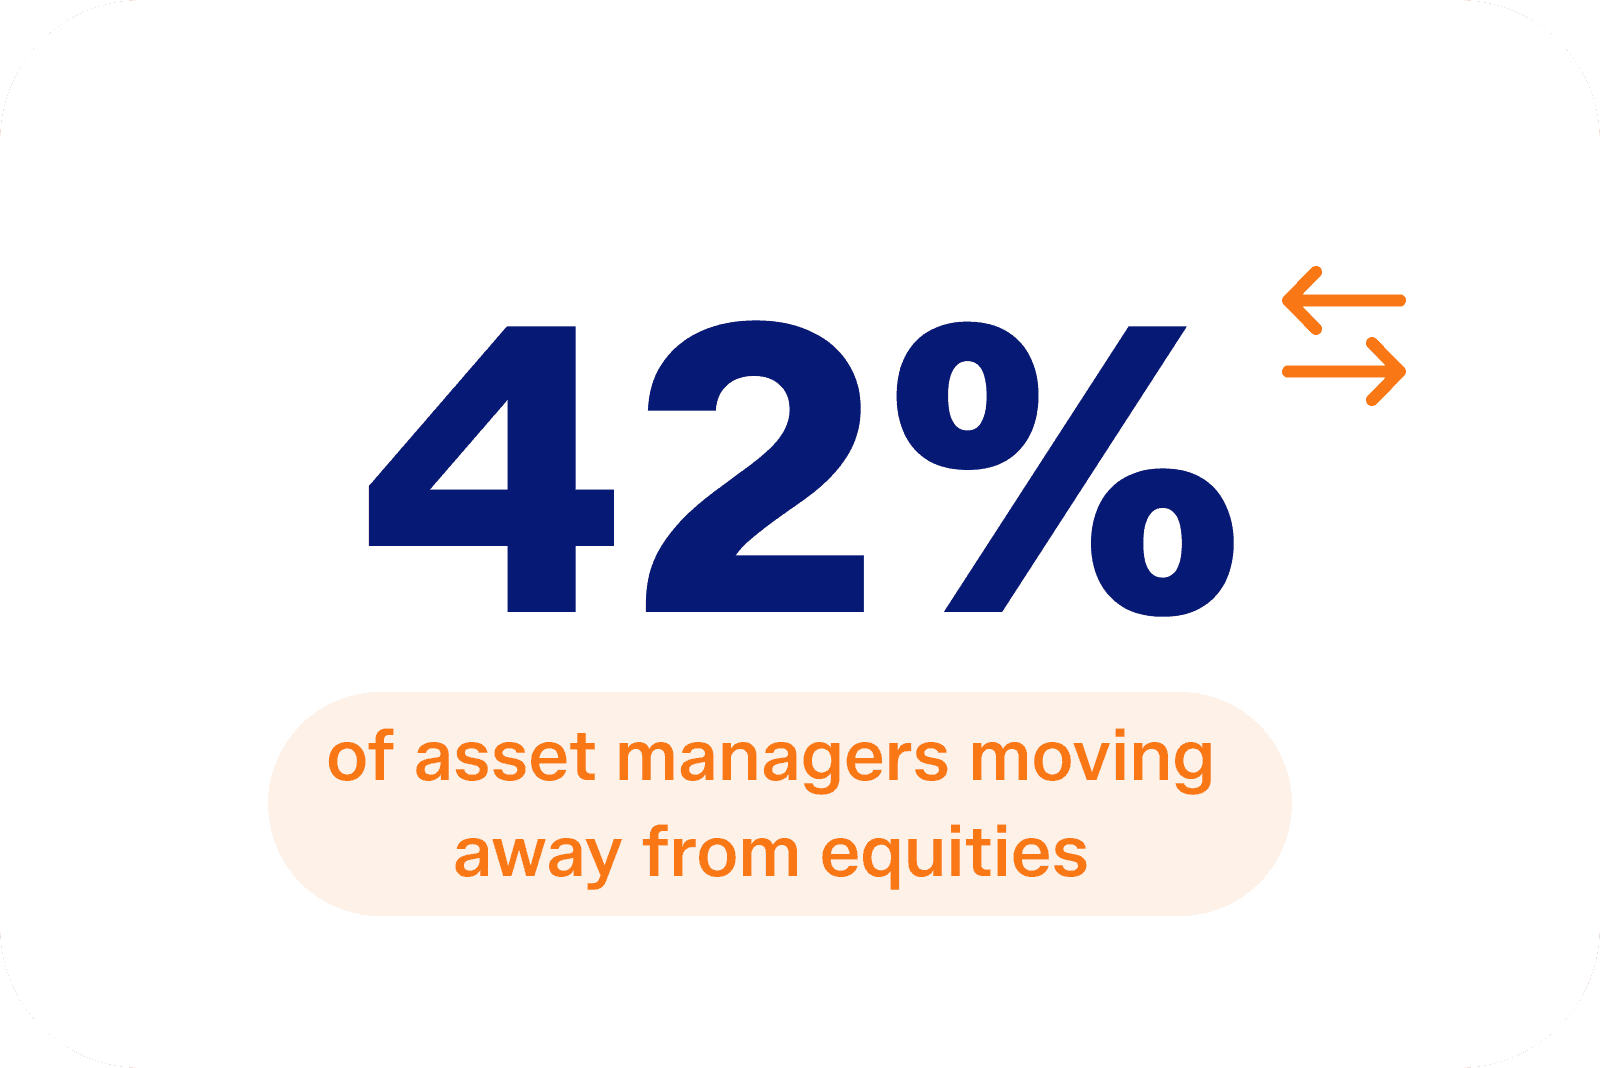
Growth is moving into more complex products, changing the pressure profile for investment accounting.
Firms are shifting towards private credit, project finance, cryptocurrencies and structured products in search of alpha.
NAV pressure is building
Valuation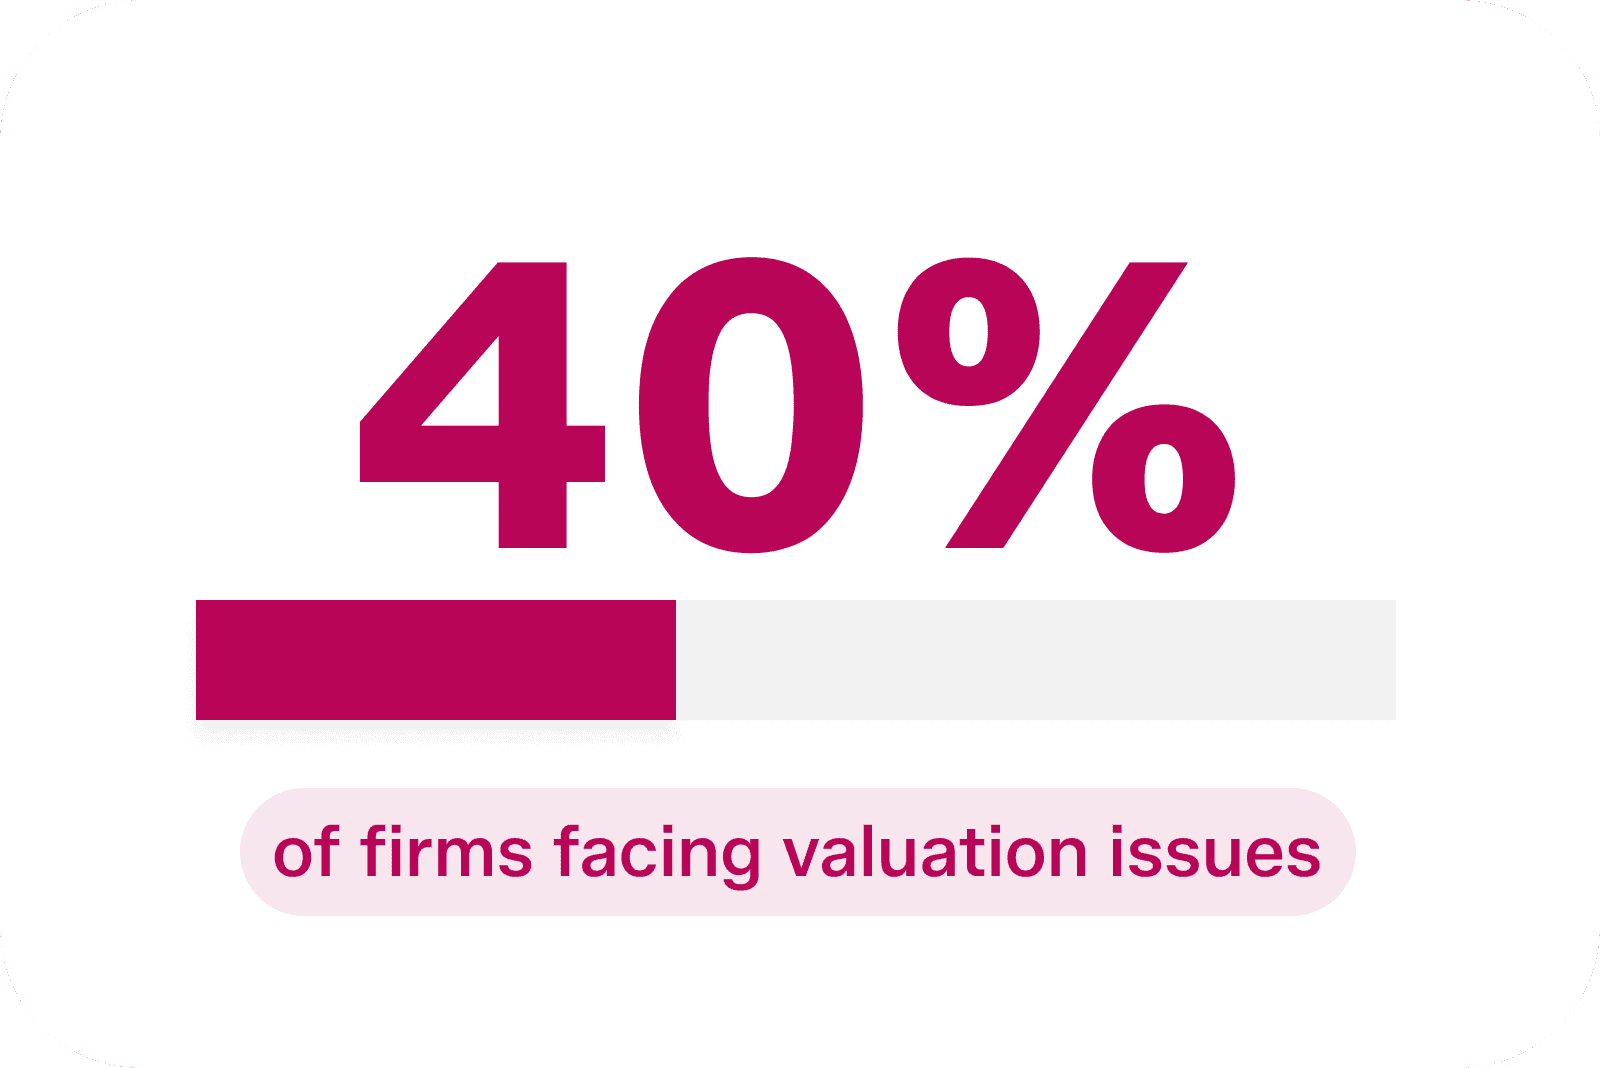
Fund valuation is becoming more difficult exactly where growth is strongest.
52% also say NAV issues are now affecting commercial distribution relationships.
Fragmentation remains widespread
Platforms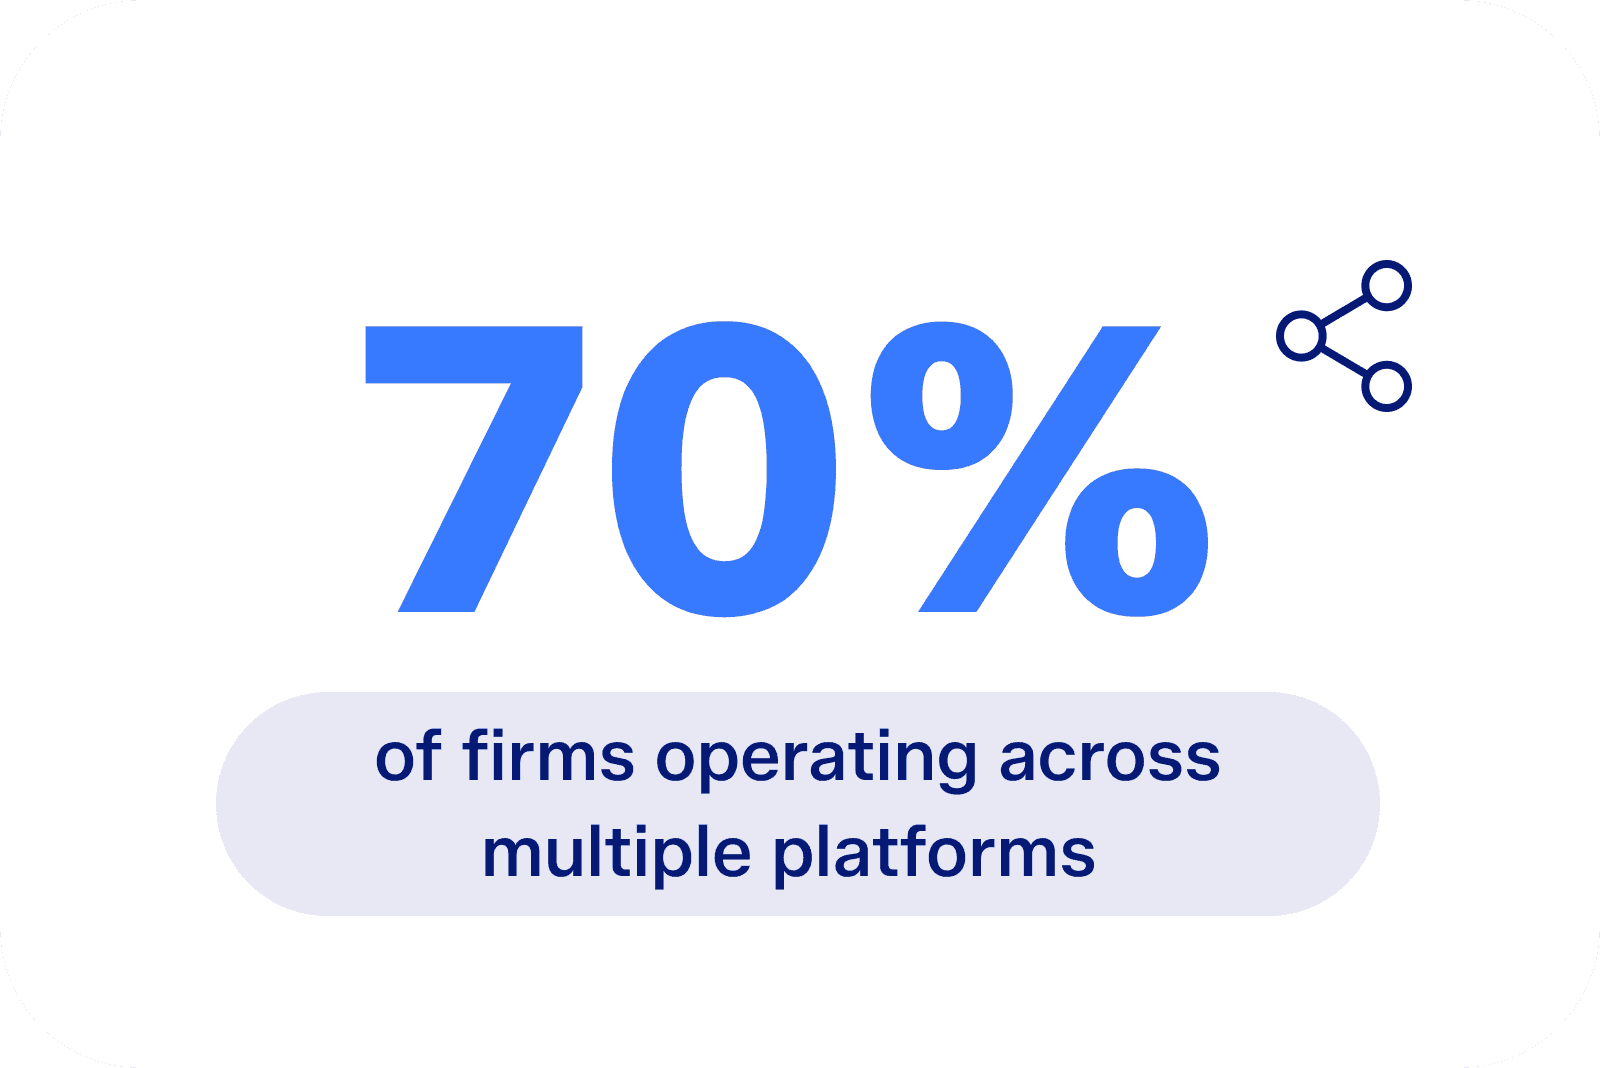
Platform fragmentation remains a structural issue at the point where firms need more control, not less.
86% expect to accelerate NAV production by 2028, increasing pressure on already fragmented models.
Investment accounting is coming under pressure from several directions at once. Product growth is shifting into more complex markets, dealing and settlement cycles are tightening, and expectations around NAV resilience are becoming harder to absorb with fragmented platforms and manual workarounds.
Where are the biggest pressure points in investment accounting today? How are firms responding as valuation complexity, platform fragmentation and commercial pressure on NAV production continue to build?
These key findings, developed with FIS®, draw on industry responses on product and asset class change, valuation pressure, fragmented platforms, tighter operating expectations and operating model redesign. They provide a clearer view of where pressure is building and where structural change is already under way.
The research highlights:
T+1 dealing cycles are the #1 threat to NAV resilience in 2026 for 64% of firms.
48% of firms are now ready to invest in a contingent NAV provider.
86% of firms expect to accelerate their NAV production by 2028.
NAV-related spend now makes up 3.5 basis points in the fund TER.
Keep reading — it's free
Verify your email to read this content
Ask the Xchange AI
Have a question about our research? Ask our AI assistant for specific insights.
Discover More
View All Insights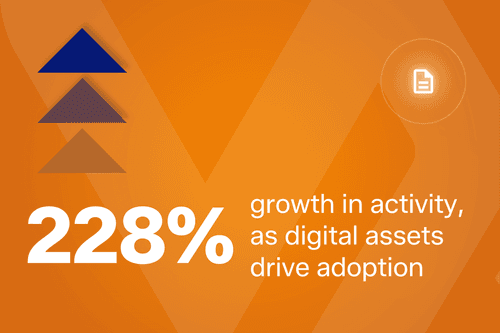
Report
12 October 2026
Explore how the tokenised equities market is developing and the opportunities shaping wider adoption.
Podcast
8 October 2026
What surprised us at Sibos? The post-trade triangle of T+1, 23x5 and tokensiation, making up the majority of work in the industry
Xchange brief
8 October 2026
Two deadlines, different scopes: how to understand cash and repo clearing, test your transactions, plan changes your business needs?
Webinar
7 October 2026
Join BNY, Broadridge, DTCC and SIFMA to explore what remains ahead as the U.S. Treasury central clearing deadlines approach.
Report
6 October 2026
See how T+1 preparation practically differs across segments as Europe enters the final year before the 2027 transition.