Xchange brief
•Published 25 Sept 2026

Swift standards release delay: what does it mean for EU T+1?

Swift deferred its November 2026 release, forcing a quick reaction from the securities industry dependent on it for Europe's move to T+1.

Xchange premium
Swift standards release delay: what does it mean for EU T+1?

Snapshot of this brief

  • Why Swift postponed its November 2026 Standards Release, and at whose request
  • Which securities and funds changes have been pushed back to 12 June 2027
  • How the delay compresses the testing window before EU T+1 goes live on 11 October 2027
  • What the new repo "gating event" means for securities financing transactions under T+1
  • What T+1 programme leads should do next, and by when

Subscription Required

Create an account and subscribe to Xchange to access premium research insights.
1. The headlines

  • On 21st September, Swift confirmed that is has postponed its November 2026 Standards Release. It’s only the 3rd time that this happened.
  • The primary cause was the payments industry's lack of readiness. Firms were not ready to remove unstructured postal addresses from ISO 20022 payment messages.
  • Following the confirmation of the delay, securities-related changes have been decoupled from the broader release. These include changes to support the EU's transition to T+1. They are now scheduled for release on 12 June 2027. The industry must now absorb two distinct Swift releases in a single calendar year.
  • Central banks have mirrored the shift. The Bank of England has deferred its linked Real-Time Gross Settlement (RTGS) release. The Eurosystem has shifted its TARGET Services release timeline. The US Federal Reserve has postponed its next Fedwire ISO 20022 phase to late 2027.
  • For EU T+1, the go-live remains 11 October 2027. However, the delay compresses the post-implementation testing runway. Firms now have a tight four-month window.

2. What is the annual Swift standards release?

Swift runs one coordinated global update to its messaging stack every November. This is known as the Standards Release (SR). The window synchronises updates across legacy MT formats and newer ISO 20022 MX schemas. These schemas are used across payments, securities, and trade.

The release is governed by Swift’s Standards Committees. Governance also involves the Securities Market and Practice Group (SMPG), financial market infrastructures (FMIs), and domestic RTGS operators. This single cutover date keeps interconnected global trading parties fully interoperable.

3. Why was SR2026 postponed, and why does it matter to securities firms?

A formal request from the payments industry led to the postponement. The trigger was uneven global readiness for retiring unstructured postal addresses in ISO 20022 payment messages. Rather than split the release, Swift deferred cross-border payments in full until SR2027. This pushed SR2026, covering securities and funds, into 2027.

Securities participants rely on the annual cycle to maintain baseline integrity. They also benefit from improved messaging capabilities each year. FMIs often synchronise their own functionality, release, and testing schedules to the Swift release date. A delay at the Swift level therefore impacts FMI and bank test plans and budgets.

This specific release is critical. It represents the final messaging baseline before Europe adopts T+1 in October 2027. Several readiness milestones depend on SR2026 changes, and it now adds pressure to the project agenda for firms in 2027 as they prepare for the T+1 transition. 
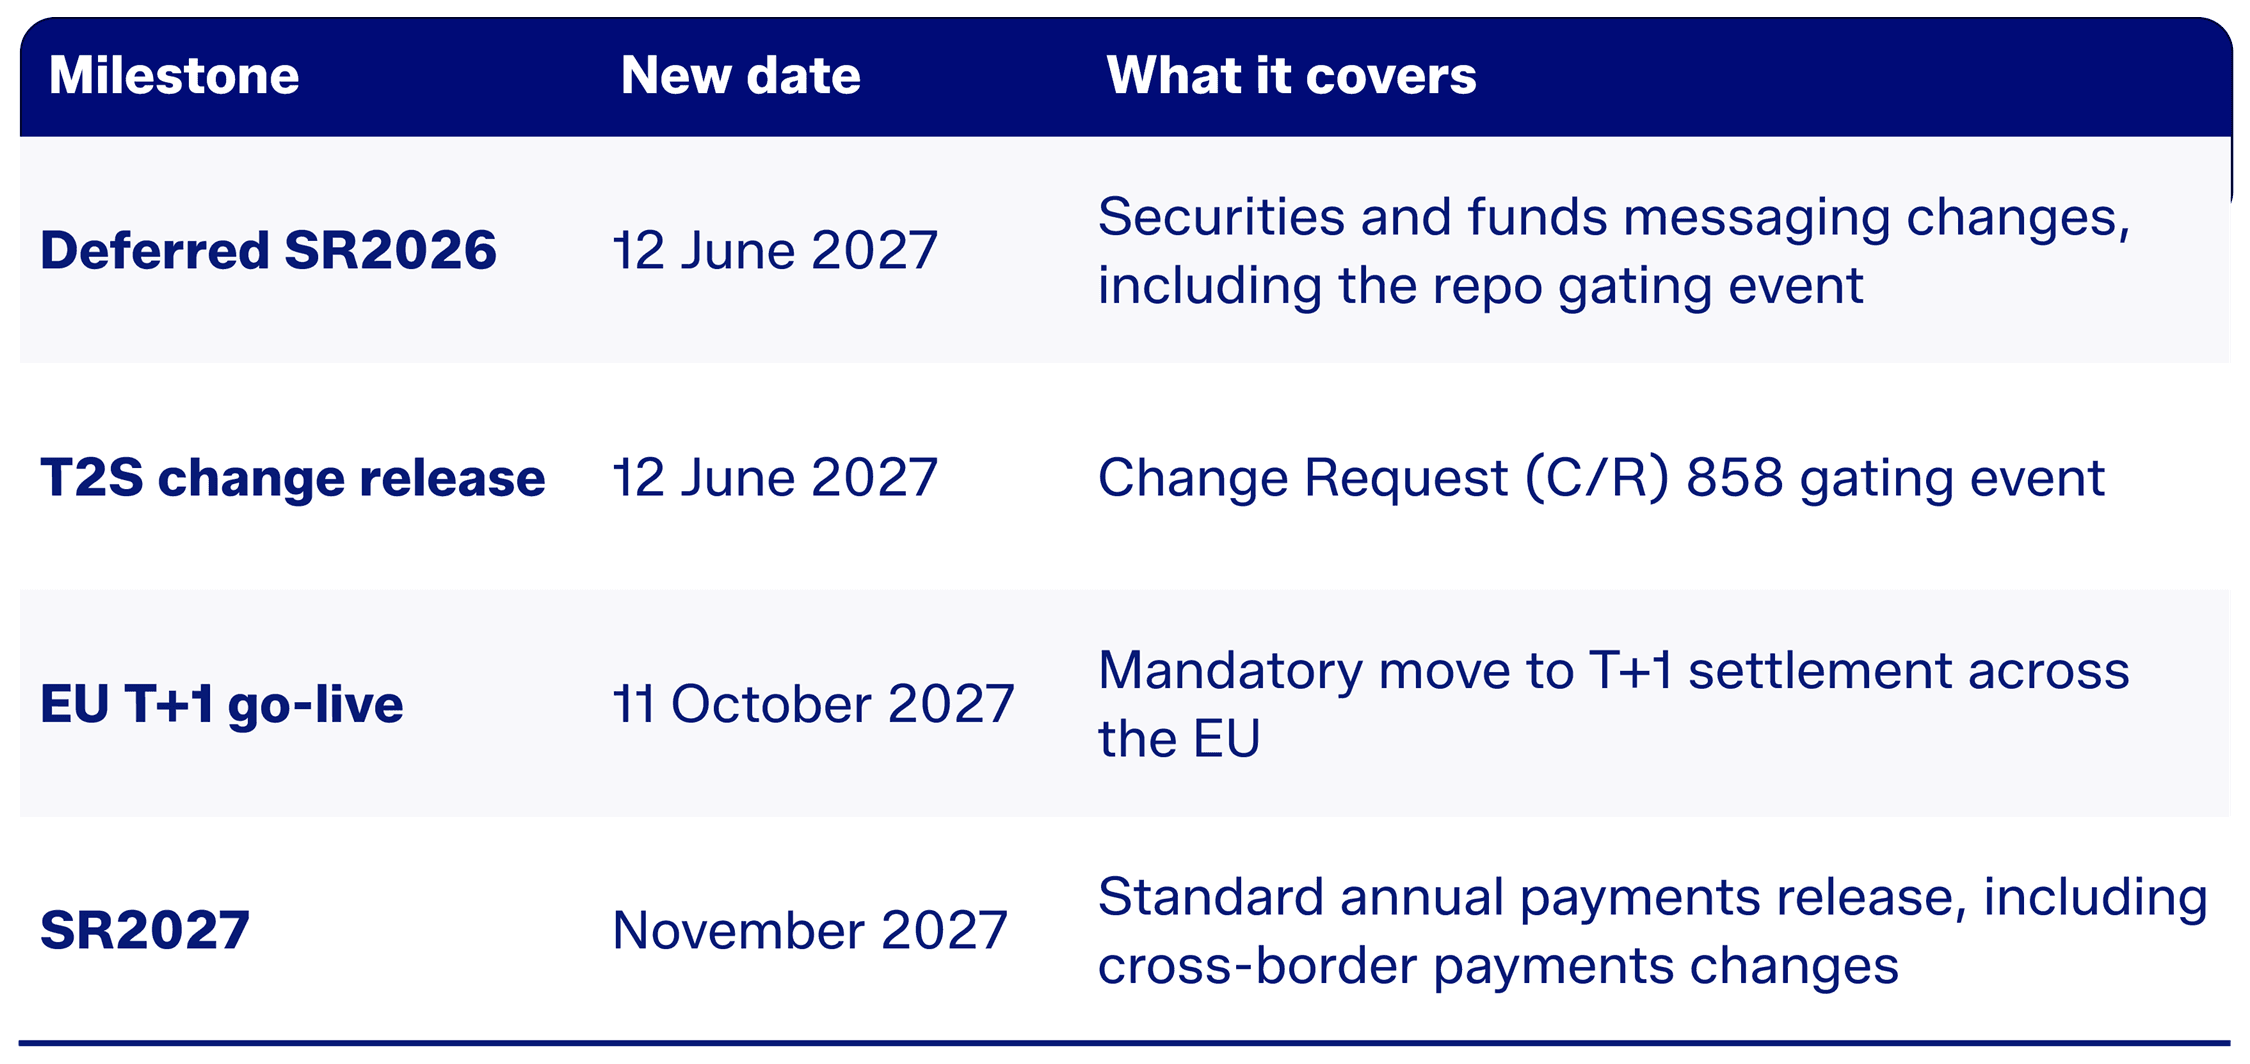
Table 1: three 2027 milestones bring a congested calendar for the securities industry

Table detailing financial milestones, their new dates, and what each event covers.

4. What securities changes were due in SR2026?

4.1 The repo gating event

This is a solution to protect liquidity, capital, and settlement efficiency. It covers securities financing transactions settling in the European Union (EU).

  • The challenge: under T+1, Securities Financing Transactions (SFTs) effectively become T+0. Most EU (I)CSDs commence settlement at night via Night-Time Settlement (NTS). These same-day repos will miss the NTS window.
  • The netting problem: Target2-Securities (T2S) NTS runs highly optimised, technical netting sequences. Transactions are netted multilaterally. This dramatically reduces the liquidity and collateral needed to settle huge repo notionals and broader flow committed for settlement. Missing NTS forces trades into daytime Real-Time Settlement (RTS). RTS processes transactions on a gross, transaction-by-transaction basis. Funding on a gross basis can create severe cash and credit blockages. This spikes the risk of systemic settlement fails and a chain reaction of failures that could lock up market liquidity.
  • The solution: the EU T+1 Industry Committee designed a dedicated daytime settlement window. This is called a "gating event". SFTs flagged with the new Swift identifier "GATE" will be temporarily held. They will then be settled simultaneously in this dedicated batch at 11.00 CET. This allows T2S algorithms to net the flow and optimise liquidity. Swift was expected to release the GATE identifier in SR2026.
  • The new timeline: Swift will deliver the GATE identifier on 12 June 2027. This matches the European Central Bank's (ECB) deployment of its June 2027 T2S Release. Dedicated industry testing for the gating event opens immediately after the June drop. Testing will run until 1 October 2027.

4.2 Asset servicing updates

The following revisions were also scheduled to be implemented in the SR2026:

  • Corporate actions (MT 564/566): new formatting rules for granular decimalised cash-in-lieu and fractional payouts, plus tracking fields to meet Shareholder Rights Directive (SRD II) mandates
  • Buyer protection (MT 565): strict time-boundary parameters to standardise instructions for corporate elections approaching hard market cut-offs
  • General meetings (seev): native XML data structures to automate proxy voting confirmations and standardise identity disclosure requests
  • Market claims (sese.023/.024): enhanced field logic to auto-detect and link claim events on pending, unsettled trades straddling the T+1 shift

These will now be included in the deferred SR2026 release (scheduled for 12th June 2027).

5. What next?

Swift will implement the deferred SR2026 for securities and funds on 12 June 2027. This supports the T2S release.

The EU's move to T+1 remains unchanged on 11 October 2027. However, the delay compresses the window available for messaging-dependent testing. Operations and technology teams face three volatile milestones in quick succession. These are the deferred SR2026 drop in June 2027, the T+1 migration in October 2027, and the standard SR2027 payments release in November 2027.

This is not simply a technical delay. It resets the entire 2027 delivery calendar for European post-trade change, and firms that plan around the old assumptions risk being caught out.

The UK and EU T+1 taskforces published their implementation plans assuming a stable November 2026 Swift release, and so the industry will now need to re-evaluate and reconsider the specific details of the 2027 implementation plan.

In our latest EU Industry Committee T+1 readiness pulse, 64% of firms cited their dependency on other market participants as the primary challenge in meeting the T+1 requirements in October 2027. This latest delay underscores the critical importance of renewed engagement between firms, vendors and service providers. Find out more here: link

Table 2: % of firms facing challenges in meeting T+1 requirements

Question: which challenges do you anticipate in meeting the T+1 settlement cycle requirement?
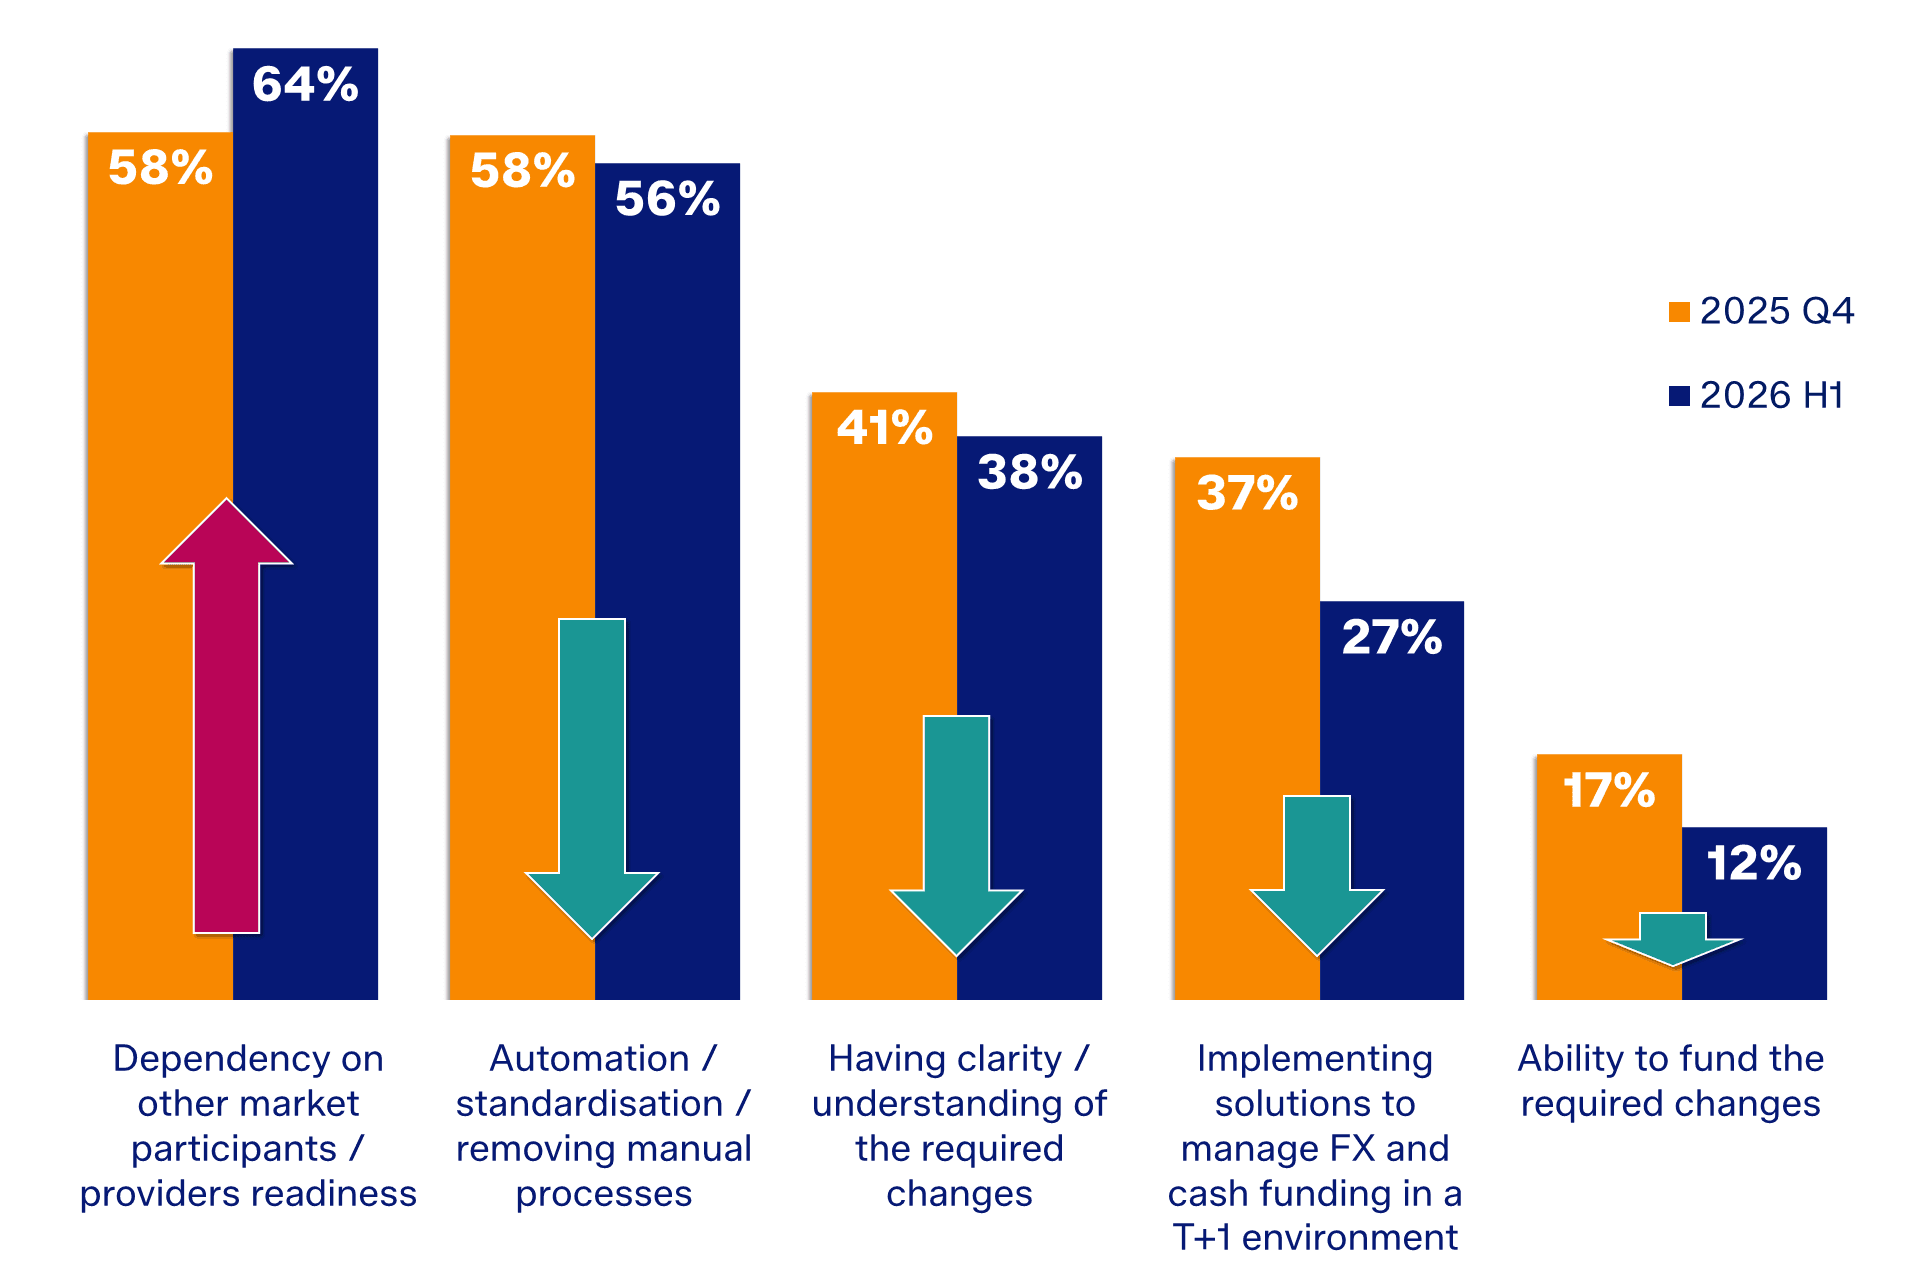
Bar chart comparing market challenges in Q4 2025 and H1 2026, with dependency increasing.

For T+1 project teams and programme managers across the industry, this means:

  1. An urgent review or your internal project deliverables to ensure that resourcing and dependencies are managed around the new roadmap
  2. Immediate outreach to custodians and CSDs to confirm that Q1 2027 remains a workable date for their testing milestones, in particular
  3. A review of firms’ own test schedules for 2027 will be critical, to ensure that clients, counterparties and vendors are all prepared as a matter of urgency


Ask the Xchange AI

Have a question about our research? Ask our AI assistant for specific insights.